Behind on Car Payments in BC? Repossession, the Seize-or-Sue Rule and Your Options Before Default
In BC a lender can usually repossess a financed car without going to court, but if it takes back a personal-use car it generally cannot also sue you for the shortfall. This guide walks through the timeline from the first missed payment to the auction, what bailiffs can and cannot do, and the real cost of each way out.
1. What happens if you fall behind on car payments in BC?
In BC, a lender can repossess a personal-use car after default without a court order, usually through a licensed bailiff, unless you have paid at least two-thirds of the amount secured. Repossession generally ends the debt: the lender cannot also sue you for the shortfall. And until the car is sold, you have a right to catch up.
That changes what you should do this week. Letting the car go usually will not leave you owing a shortfall, but it costs you the car and marks your credit file for years.
You are not alone. Equifax Canada's Q2 2026 report put the national 90-day-plus auto-loan delinquency rate at 1.10%. BC's 90-day-plus rate on non-mortgage debt (by balance) was 1.57%, which is 3.27% higher than a year earlier.
2. The timeline, from first missed payment to sale
Your contract defines default; some treat one missed payment as default. BDO, a licensed insolvency trustee, writes that two or three missed payments in a row make repossession likely. The steps after seizure are set by statute.
| Stage | What happens | Your best move |
|---|---|---|
| First missed payment | Late fee and calls. Past 30 days, lenders can report a rating of 2. | Call the lender first; ask for a deferral in writing. |
| Two to three payments behind | Ratings of 2 or 3. The account can be assigned to a licensed bailiff. | Get a payout letter and an appraisal (section 6). |
| Seizure | No court order needed unless two-thirds is paid. | Retrieve belongings; keep every document. |
| Notice of disposition | At least 20 days before sale. It must state the arrears, the full balance and the expenses. | Reinstate, redeem or let it go (section 5). |
| Sale | Proceeds pay expenses first, then the debt. Any surplus goes to other secured creditors, then to you. | Demand a written accounting; it is due within 30 days. |
Statutory steps from the Personal Property Security Act, sections 58 to 62, as of late September 2026. Lender timing varies.
3. What the lender and bailiff can and cannot do
Section 58 of the PPSA lets the lender take possession "by any method permitted by law". The Act sets no notice period before seizure (check your contract), so a bailiff can tow the car from a street, a parking lot or even your driveway. The limits:
- The two-thirds rule. If you have paid at least two-thirds of the total amount secured on a consumer-goods loan, the lender must not seize without first getting a court order (section 58(3) and (4)). How the total is counted depends on your contract; ask the lender for the figure in writing.
- Licensed conduct rules. Bailiffs repossessing under a contract, without a court order, must be licensed by Consumer Protection BC. They cannot harass you, use threatening or coercive language, or mislead you. They cannot remove personal property from your home without an adult resident present, or move seized property more than 100 km without your written consent or the regulator's.
- Your home is off limits without consent. In one BC case summarized by Clicklaw (a repair-lien seizure, not a car loan), a bailiff slipped into a locked apartment garage behind another tenant. The court held the garage was part of the debtor's home, ruled the entry and repossession unlawful, and ordered the car returned. A driveway is different: in another case, a peaceful repossession from a private driveway was held not unlawful.
- Fees. Reasonable bailiff fees, such as towing and storage, can be added to the amount owed.
Your belongings. The loan secures the car, not what is in it. Call the bailiff company the same day to arrange pickup of your things and the glovebox paperwork.
4. Seize or sue: what it means in dollars
For consumer goods (used mainly for personal, family or household purposes), section 67 makes the lender choose: take the car, by seizure or surrender, or sue you for the debt. If it takes the car, your unperformed obligations under the agreement are extinguished.
| Example: personal-use car | Amount |
|---|---|
| Balance owing at default | $22,000 |
| Lender sells the car at auction | $14,000 |
| Reasonable seizure, storage and sale expenses (paid first) | $1,500 |
| Applied to the debt ($14,000 − $1,500) | $12,500 |
| Shortfall ($22,000 − $12,500) | $9,500 |
| What you owe after the sale in BC | $0: extinguished under section 67(2) |
Illustrative figures. Expense order from PPSA section 59(2). Without section 67, the $9,500 shortfall would remain a debt.
If the lender sues instead, its security interest in the car is extinguished, and it must discharge the registration within a month (section 67(10)). If it later has the car seized and sold to enforce the judgment, it can recover no more than that sale brings in (sections 67(6) and (7)).
The exceptions. A court can lift the protection if the car was substantially damaged through wilful or reckless acts or neglect. The lender can also pursue you for the value of any part that was removed and not replaced. A car used mainly for business is not consumer goods. How this interacts with refinancing and consumer proposals is in getting out of a high-interest car loan.
One check: the notice of disposition must not mention a deficiency the lender has no right to collect (section 59(9)). If yours does, ask in writing which exception the lender relies on.
5. Reinstate or redeem: getting the car back
Until the car is sold or contracted for sale, section 62 gives you two ways back. The 20-day notice must state both amounts, so you should not have to guess.
| Example | Reinstate | Redeem |
|---|---|---|
| What you pay | Arrears only: 3 × $520 = $1,560 | Full balance: $22,000 |
| Plus reasonable expenses | $1,500 | $1,500 |
| Total to get the car back | $3,060 | $23,500 |
| What happens next | The original loan carries on; the late payments stay on your file | The loan is paid off and the lien discharged |
| Limit | Twice a year on a loan longer than 12 months | Not limited |
Illustrative figures. Reinstatement applies when all the collateral is consumer goods, and it ignores any acceleration clause (PPSA section 62(1)(b)). You lose either right only if you agree in writing after default, so read anything the lender asks you to sign.
Reinstate only if whatever caused the missed payments is fixed. Redeeming usually needs a refinance, which is hard to arrange inside 20 days with fresh lates on your file.
6. Your options before default, ranked
Ranked from least to most damage to your credit file, assuming the payment is genuinely unaffordable.
| Option | Cash cost | Credit effect | Car after? | Best when |
|---|---|---|---|---|
| 1. Deferral or revised plan | Low; extra interest | Often minimal if agreed in writing before you miss; ask how it is reported | Same car | Short, temporary income gap |
| 2. Sell to a dealer, lien paid out | Any shortfall, paid at sale | Loan closes paid; no repossession | No | Equity, or a small gap you can cover |
| 3. Trade down | Shortfall rolled into a smaller loan | Old loan closes paid; new loan | Cheaper car | You need a car and the gap is modest |
| 4. Refinance | Fees; possibly a longer term | New inquiry and new loan | Same car | Your file has recovered since you signed |
| 5. Private sale | Shortfall; more time and risk | Loan closes paid | No | You have weeks, not days |
| 6. Voluntary surrender | Generally $0 on a personal-use car | Rating 8 on your file for years | No | Deep negative equity and no way to pay |
General guidance as of September 2026, not legal advice. A consumer proposal deals with unsecured debt; to keep the car you keep paying the car loan.
Selling with a loan is normal. A dealer pays the lender from the sale and the registered lien is discharged. Ask your lender for a payout letter, then get an offer on your car or start at sell or trade. Mechanics: trading in a car with a loan and trade-in vs private sale.
If you need a car, a soft-pull pre-qualification shows what a lender would approve before you commit. Recent lates narrow the field; see bad credit financing.
7. The negative-equity math, side by side
Negative equity means you owe more than the car is worth, a risk the FCAC ties to long loan terms and the VSA to small down payments and rolled-over balances. One illustrative case, four exits:
Example: payout $18,000 at 14% with 48 months left, so the payment is $491.88. The dealer appraisal is $14,000, so negative equity is $18,000 − $14,000 = $4,000.
| Exit | Monthly payment | Still to pay | Outcome |
|---|---|---|---|
| Keep paying | $491.88 | $23,610 over 48 months | Keep the car if you can sustain it |
| Sell to a dealer, cover the gap | $0 | $4,000 at the sale | No car; clean close |
| Trade down to a $12,000 all-in car, 48 months at 14% | $437.22 | $20,987 | Saves $54.66 a month |
| Same trade down, 60 months at 14% | $372.29 | $22,338 | Saves $119.59 a month, one more year |
| Voluntary surrender | $0 | $0 on a personal-use car | No car; rating 8 on your file |
Illustrative, not a quote. Trade-down amount financed: $12,000 price − $14,000 trade credit + $18,000 payout = $16,000. A trade-in reduces the taxable price at a dealer (Bulletin PST 308). Here the trade credit exceeds the price, so the example assumes no sales tax is added; confirm the tax lines on your bill of sale. Standard amortisation, monthly rate = APR ÷ 12, no fees.
Two honest conclusions. Trading down at the same rate saves less than people hope: the $4,000 rides along, the new loan is about 133% of the car's value, and many lenders limit how far above value they will lend. And in BC, surrender is the lowest-cash exit when you are deep underwater, which is why it should be your decision, not something that happens to you.
Available right now
Lower-cost cars to trade down into
Live from our New Westminster showroom. Every one is Spinny Assured with a 150-point inspection, 6-month warranty, 7-day exchange and CARFAX.
 2025 Toyota Corolla LE | No Accidents, Local BC8,451 km • Gasoline$27,995
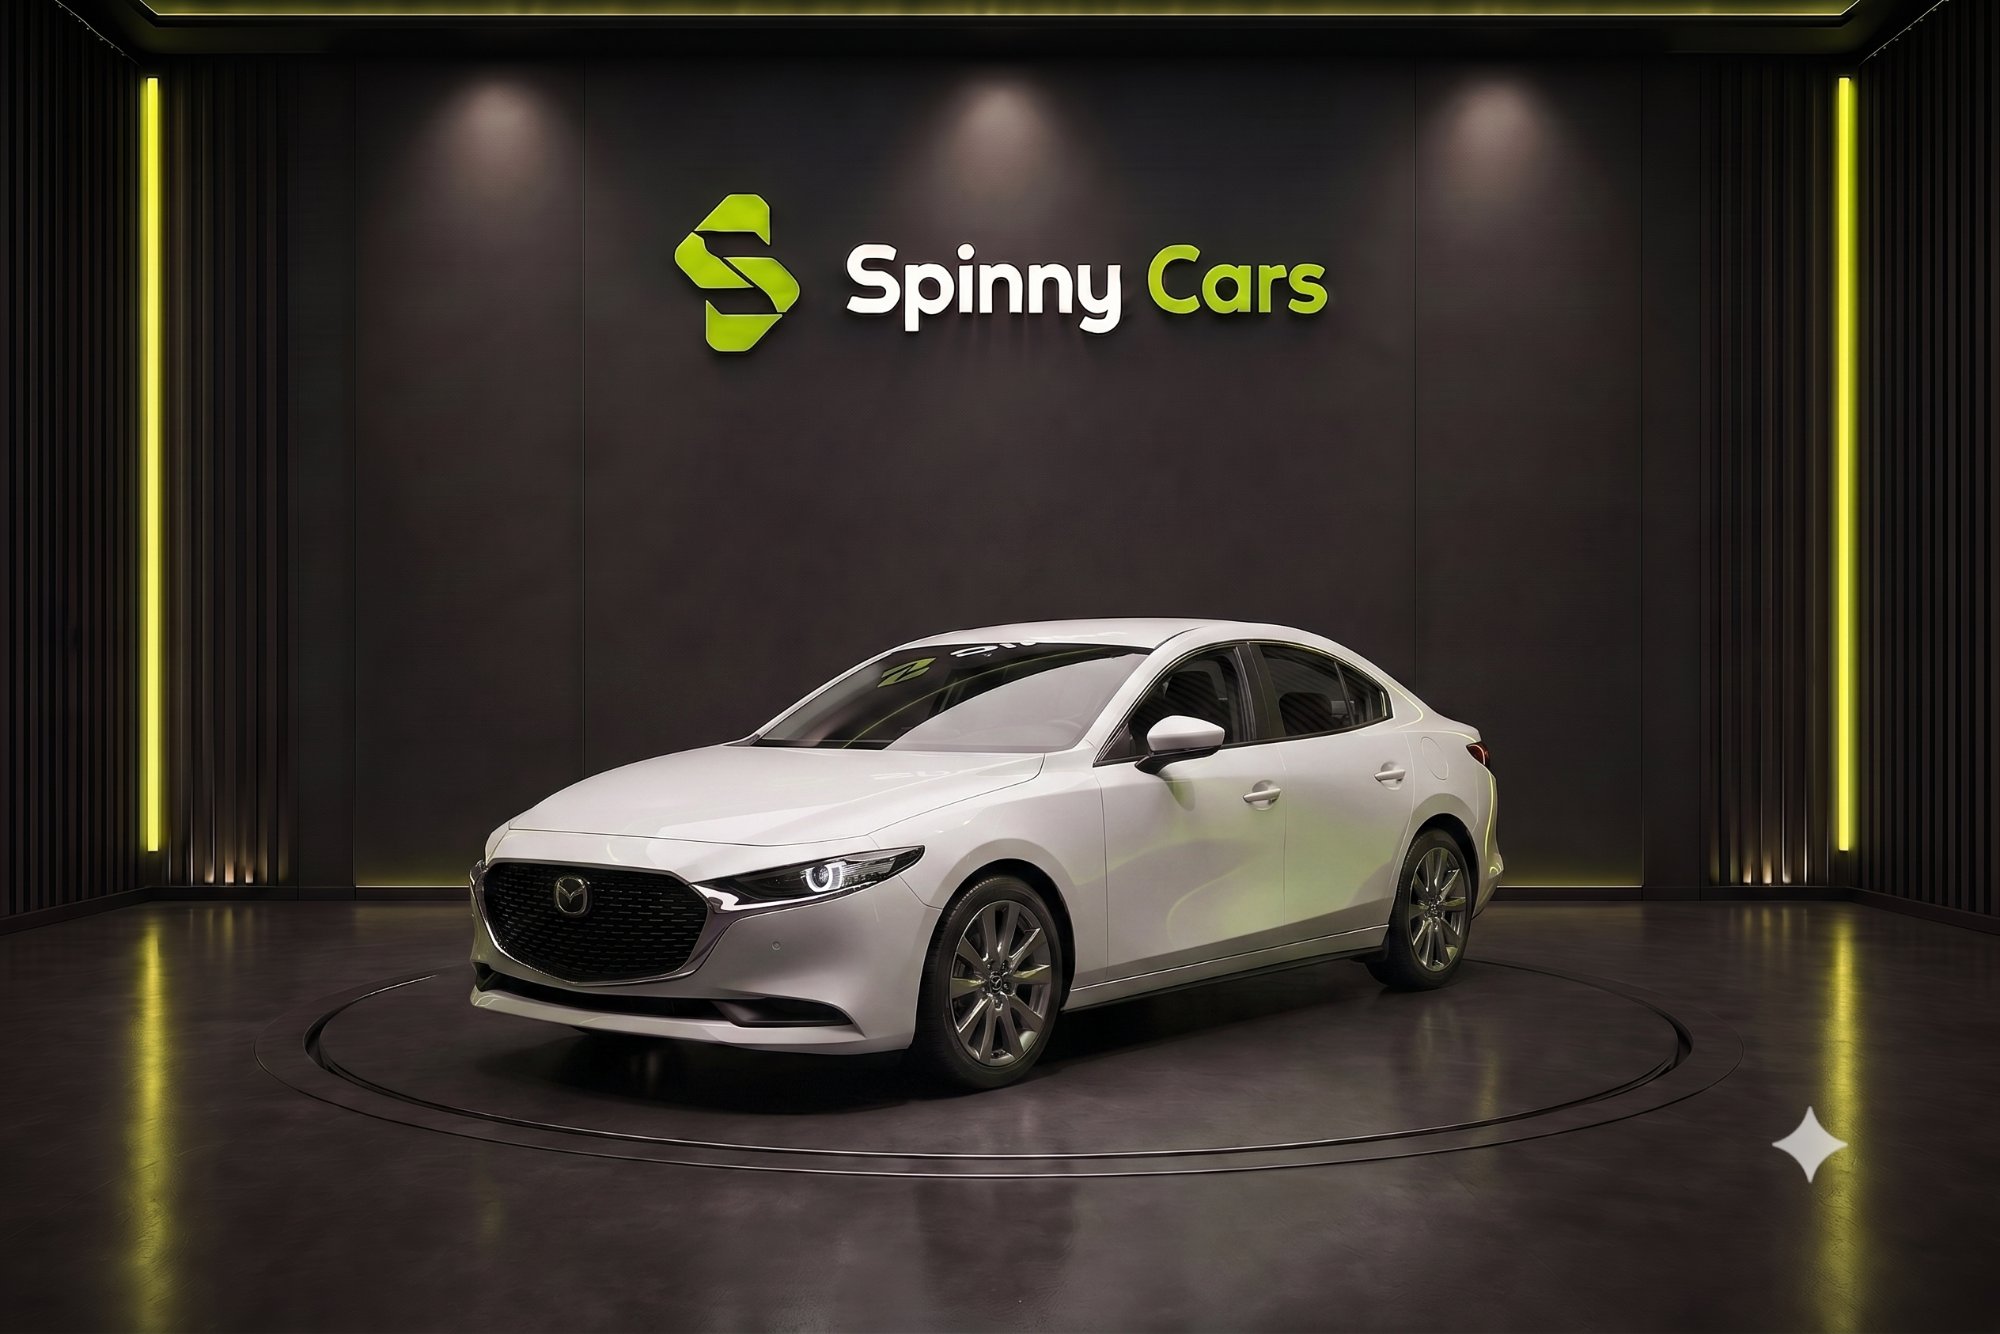 2025 Mazda Mazda3 GS | Brand New435 km • Gasoline$29,995
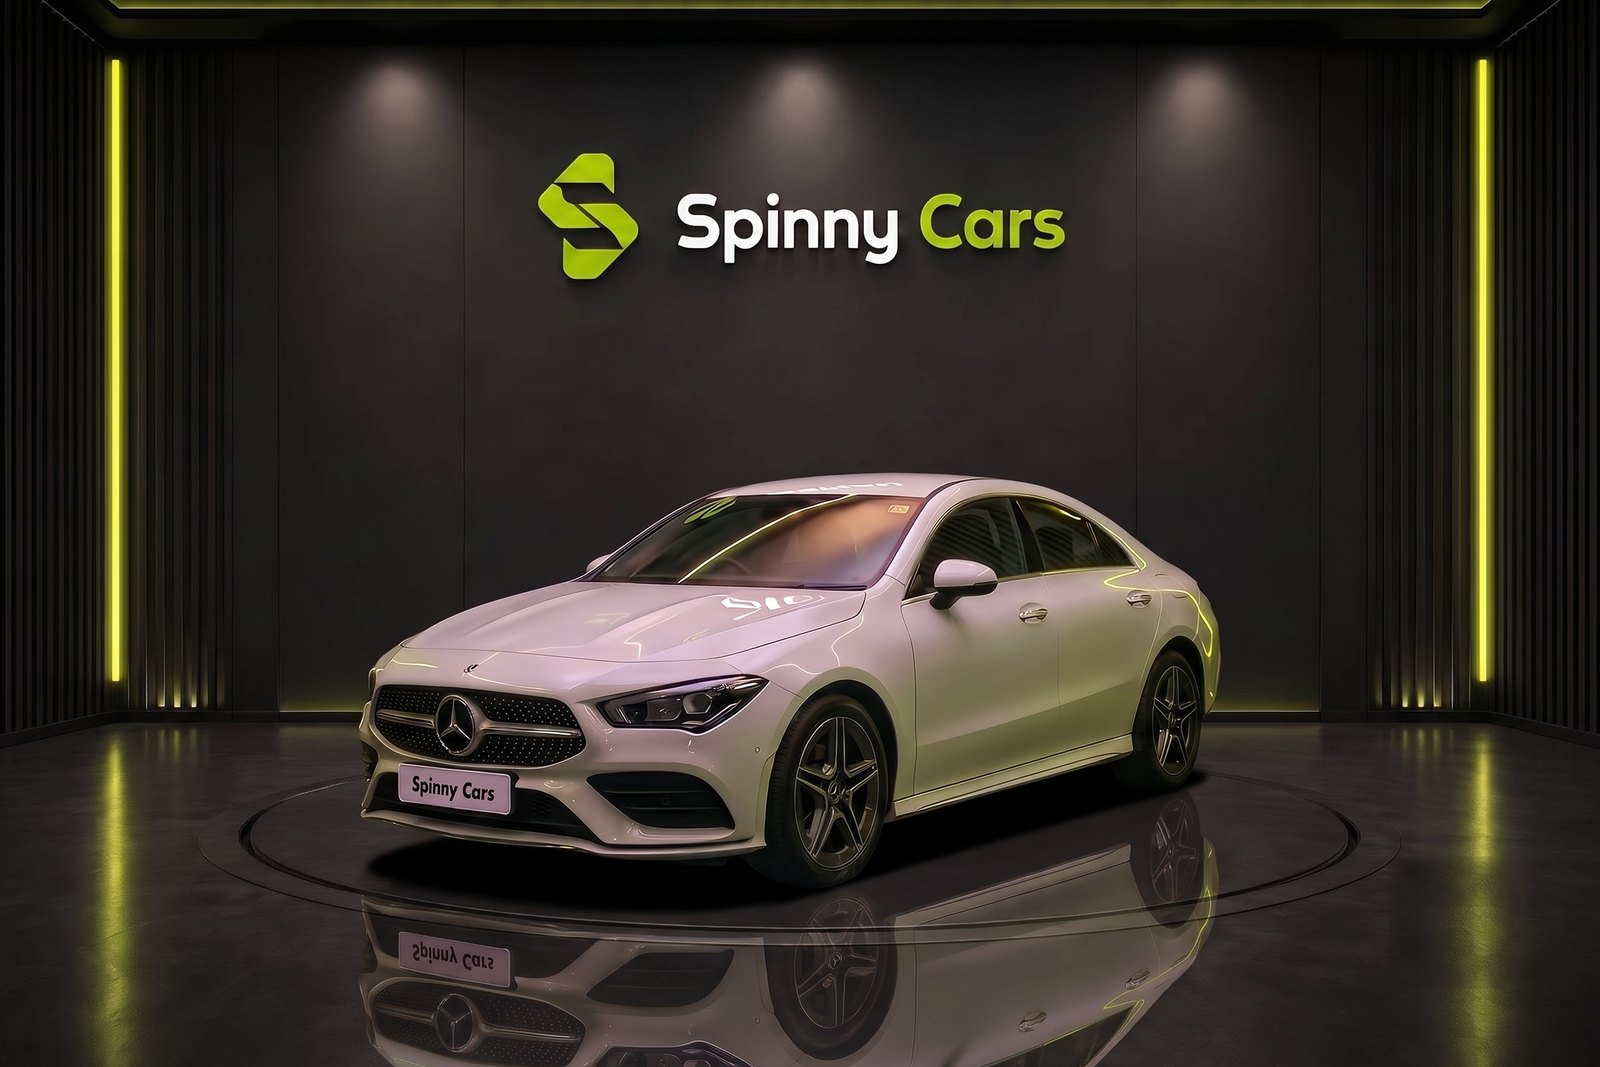 2026 Mercedes-Benz CLA 25030,910 km • Gasoline$36,995
 2018 BMW 330i M Sport105,124 km • Gasoline$19,995
 2023 Hyundai Elantra Preferred Sun & Tech66,254 km • Gasoline$23,995
 2025 Hyundai Elantra Preffered, One Owner, Local BC51,509 km • Gasoline$23,995
8. What each path does to your credit file
Lenders report a car loan as an installment (I) account with a rating number, which is what the next lender reads.
| Rating | Equifax meaning |
|---|---|
| I1 | Paid within 30 days, or not over one payment past due |
| I2 to I4 | 30 to 120 days, or two to four payments past due |
| I5 | At least 120 days overdue, not yet rated 9 |
| I8 | Repossession, voluntary or involuntary |
| I9 | Bad debt; placed for collection |
Ratings from the Equifax Consumer Credit Report User Guide.
Equifax Canada's retention rules keep late payments for up to six years from the date reported. That is why option 2 beats option 6 if you can cover the gap: a sale closes the loan as paid; surrender writes an 8.
9. After seizure: ICBC, co-signers and leases
- Insurance and plates. To cancel Autoplan coverage, ICBC asks you to visit an Autoplan broker with primary and secondary ID, the licence plates (or a police file number if they were lost or stolen) and the owner's certificate. The sooner you cancel, the more you may get back, so ask for the plates when you collect your belongings. Do not just stop paying premiums: in a 2025 Civil Resolution Tribunal case reported by Canadian Underwriter, a driver whose plates went to auction with his repossessed car could not cancel for months, and the rest of the year's premium came due at once. The tribunal held ICBC only one-third responsible.
- Co-signers. When the lender seizes or accepts surrender of consumer goods, section 67(2) also extinguishes the obligations of a guarantor or indemnitor. Before that point, a co-signer is on the hook for missed payments.
- Leases. Part 5 of the PPSA, which contains the seize-or-sue rule, does not apply to a lease for more than one year that does not secure payment of an obligation (sections 3 and 55). A true lease may fall outside it, leaving its early-termination terms to govern; a lease that is really financing is not. Get legal advice before handing one back. See lease buyout vs trade-in.
Frequently Asked Questions
How many car payments can you miss before repossession in BC?
There is no fixed number. Your contract defines default, and some treat one missed payment as default; insolvency trustees such as BDO say two or three in a row make repossession likely. Once you have paid two-thirds of the amount secured on a personal-use car, the lender needs a court order to seize it.
Can a bailiff take my car without a court order in BC?
Yes, in most cases. BC's Personal Property Security Act lets a lender repossess after default without going to court, unless the car is for personal use and you have paid at least two-thirds of the amount secured. Bailiffs working without a court order must be licensed by Consumer Protection BC and cannot harass you.
Can the lender sue me for the balance after repossessing my car in BC?
Generally no, for a car used mainly for personal or family purposes. Under section 67, a lender that seizes the car or accepts its surrender extinguishes your remaining obligation. Exceptions include wilful or reckless damage, removed parts, and vehicles used mainly for business.
Can I sell my car if I am behind on payments?
Yes, until it is seized. A dealer pays your lender directly from the sale and the lien is discharged. If the car is worth less than the payout, you cover the difference at the sale or roll it into a cheaper car's loan.
Is voluntary repossession better than waiting for the bailiff?
It gives you control over timing and your belongings, and in BC it generally ends the debt on a personal-use car. It is not better for your credit: Equifax's rating 8 covers voluntary and involuntary repossession alike.
Can I get my car back after it has been repossessed in BC?
Yes, until it is sold. You can reinstate by paying the arrears plus reasonable expenses, up to twice a year, or redeem by paying the full balance plus expenses. The 20-day notice of disposition must state both amounts.
How a sale with a loan works at our New Westminster desk
Bring the car and your latest loan statement or account number to 240 12th Street; most appraisals take under 30 minutes. If you accept, we pay your lender directly and handle the lien release and ICBC transfer. Any equity comes to you by bank draft the same day or by electronic transfer, typically the next business day.
Already holding a notice of disposition? Call the lender about reinstatement first, then call us on +1 778 852 1023.
Sources & official references
This guide reflects our day-to-day experience at our New Westminster showroom and is cross-checked against official sources. Rules, rates and warranty terms change; always confirm current details with:
- BC Laws — Personal Property Security Act (ss. 59, 62, 67: notice, reinstatement, seize or sue)
- Consumer Protection BC — Bailiffs (licensing and conduct rules)
- Clicklaw Wikibooks — Tort actions (wrongful repossession, locked-garage case)
- People's Law School — A creditor wants to repossess your property
- Equifax — Consumer Credit Report User Guide (account rating codes, PDF)
- Equifax Canada — how long information stays on your credit report
- Equifax Canada — Q2 2026 consumer credit trends release (August 24, 2026)
- ICBC — Cancel your insurance (plates, refunds)
- Canadian Underwriter — CRT finds ICBC partly responsible after repossessed driver could not cancel policy (August 2025)
- BDO Debt Solutions — What happens before, during and after a car repossession
- BC Registries — Personal Property Registry (lien search)
- Financial Consumer Agency of Canada — financial risks when buying a car (long-term loans, depreciation, negative equity)
- Vehicle Sales Authority of BC — negative equity
- Government of BC — Bulletin PST 308, Vehicles (PDF)
- Office of the Superintendent of Bankruptcy — consumer proposals
Sell or trade down before it gets to a bailiff
Get a same-day offer on your car, loan or no loan. We pay your lender directly and explain your options for selling, trading down or keeping it.